


 U.S. Stocks vs. Bonds: Are Diverging Valuations Signaling a Shift?
 Indonesia Surprises Markets with Interest Rate Cut Amid Currency Pressure
 Fed Rate Hike Threatens Housing as U.S. Growth Leans on AI, Citi Says
 BOJ Set for 25-Basis-Point Rate Hike as Yen Weakness Fuels Inflation
 Oil Prices Dip Slightly Amid Focus on Russian Sanctions and U.S. Inflation Data
 Geopolitical Shocks That Could Reshape Financial Markets in 2025
 2025 Market Outlook: Key January Events to Watch
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 Fed May Resume Rate Hikes: BofA Analysts Outline Key Scenarios
 Mexico's Undervalued Equity Market Offers Long-Term Investment Potential
 Stock Futures Dip as Investors Await Key Payrolls Data
 UBS Projects Mixed Market Outlook for 2025 Amid Trump Policy Uncertainty
 Wall Street Analysts Weigh in on Latest NFP Data
 Fed Unveils Stablecoin Rules Under GENIUS Act


 Add as a preferred source on Google
If a currency had a soul, we would feel sorry for Sterling. First the Brexit risk and now (that the no deal risk is almost off the agenda) the Corbyn risk.
We don’t want to go down the route of simple Socialist bashing, but we have to accept that the UK is in a structurally fragile position. The country’s current account deficit amounts to a breath-taking 5% of GDP. That means every day the UK economy has to find someone to give it an additional loan worth GBP 300m for the party to continue. In a situation such as that it is not clever to put off one’s creditors, for example by electing someone who would - cautiously put - make an unconventional Prime Minister. The price to pay for continuously living above one’s means is to lose one’s scope to act, sometimes the political scope.
At present, Sterling benefits from anything that lowers Labour’s chances of winning the election. A Labour victory seems rather unlikely. But political forecasts have to be seen as rather unreliable in the UK, as we all learned the hard way in the last years. It is, therefore, understandable that the FX market behaves as it did with the Brexit risk: very little happens in the GBP exchange rates but the volatility (its levels and risk reversals) reflects increased event risk.
OTC Updates:
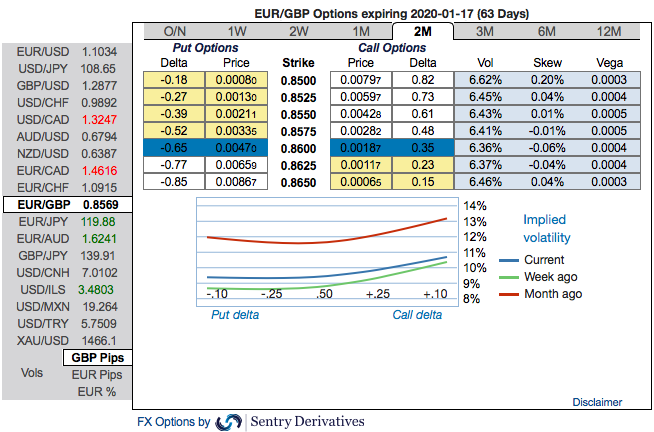
The passively skewed IVs of 2m tenors are stretched are indicating upside risks, more bids are observed for OTM call strikes up to 0.89 level.
While EURGBP risk reversals of the existing bullish setup remain intact with freshly added mild bearish shift, you see minor negative risk reversal numbers in the shorter tenor, but it should not be perceived as the bearish scenario changer. Instead, below options strategy could be deployed amid the expected turbulent condition. According to the OTC FX surface, 3-way options straddle versus ITM calls are advocated seem to be the most suitable strategy for EURGBP contemplating some OTC sentiments and geopolitical aspects.
Options Strategy: The strategy comprises of at the money +0.51 delta call and at the money -0.49 delta put options of 2m tenors, simultaneously, short (1%) ITM calls of 1w tenors. The strategy could be executed at net debit but with a reduced trading cost.
Hence, on hedging as well as trading grounds, initiate above positions with a view of arresting potential FX risks on either side but slightly favoring short-term bearish risks. Courtesy: Sentrix, Saxo & Commerzbank







