


 JPMorgan Sees ECB Raising Rates to 2.75% in December
 Japanese Yen Retreats as Dollar Rises Ahead of Fed, BOJ Rate Decisions
 FxWirePro: Daily Commodity Tracker - 21st March, 2022
 Fed Unveils Stablecoin Rules Under GENIUS Act
 BOJ Flags Import Costs and Yen Shocks as Persistent Inflation Risks
 BOJ Raises Interest Rate to 31-Year High as Yen Weakens


 Add as a preferred source on Google
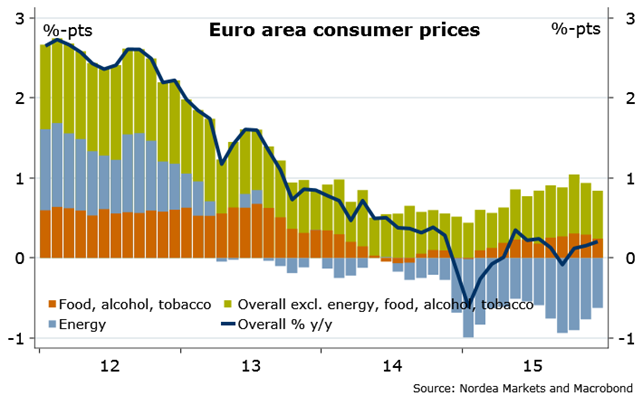
Inflation in the Euro area remained at 0.2% y/y in December. That was no surprise after the low German print yesterday. The ECB has recently shifted the focus a bit towards the core rate. The one excluding the prices for food, energy, alcohol and tobacco also remained unchanged at 0.9% (actually 0.86%).
"We expect the headline rate to rise to ½% y/y in January and to hover around that level in Q1. Still, further ECB easing measures cannot be ruled out", says Nordea Bank.
The contribution from energy prices was less negative than in November as energy prices fell more in December 2014 than in December 2015. The same effect should be visible in January pushing the headline inflation rate up to around ½% y/y.
Nothing points to a significant pick-up in core inflation. On the contrary, the inflation rate ex energy fell a tad to 0.9% y/y while service prices only increased by 1.1%, down from 1.2% in November and 1.3% in October. The point frequently made by the ECB that "signs of a pick-up of core inflation have weakened" therefore remains valid.
"We expect the headline inflation rate to hover around ½% y/y during Q1. Regarding the ECB we currently forecast no further policy easing after the substantial measures taken last year and given the ongoing recovery. However, with inflation way below target and the ECB's easing bias, further easing cannot be ruled out. The next two ECB policy meetings will be on 21 January and on 10 March. While the January meeting will most likely be for wait-and-see, March could be more interesting," added Nordea Bank.







