


 CFTC Moves to Set New Crypto Rules After CLARITY Act Failure
 AUD/JPY Range-Bound Below 110: Sellers Eye Recovery Rallies as Downward Trend Persists
 China Shuts 670 Banks as Bitcoin Eyes Financial Risks
 SEC Investor Reform Validates Barry Silbert’s Tokenization Vision
 JPY Major Currency Score: NZD/JPY, EUR/JPY, and CAD/JPY Turn Extremely Bearish
 BofA Raises Coinbase Stock Target to $203 on Stablecoin Growth
 Zcash NU7 Testnet Cuts Block Time to 25 Seconds
 Bitcoin Nears $87K as Crypto Market Gains
 Peter Brandt Flags Key XRP Breakout at $1.6572
 Zcash Mining Profits Surge as Liquidity Risks Grow
 FxWirePro: USD/JPY edges lower as investors assess Takaichi’s comments
 NZD/JPY Technical Analysis: Kiwi Pares Gains Below 89 Resistance as Bearish Momentum Accelerates
 Cardano ADA Jumps 10% as RealFi and Dijkstra Upgrade Fuel Rally
 FxWirePro: USD/CAD hits 18-month high, scope for further upside


 Add as a preferred source on Google
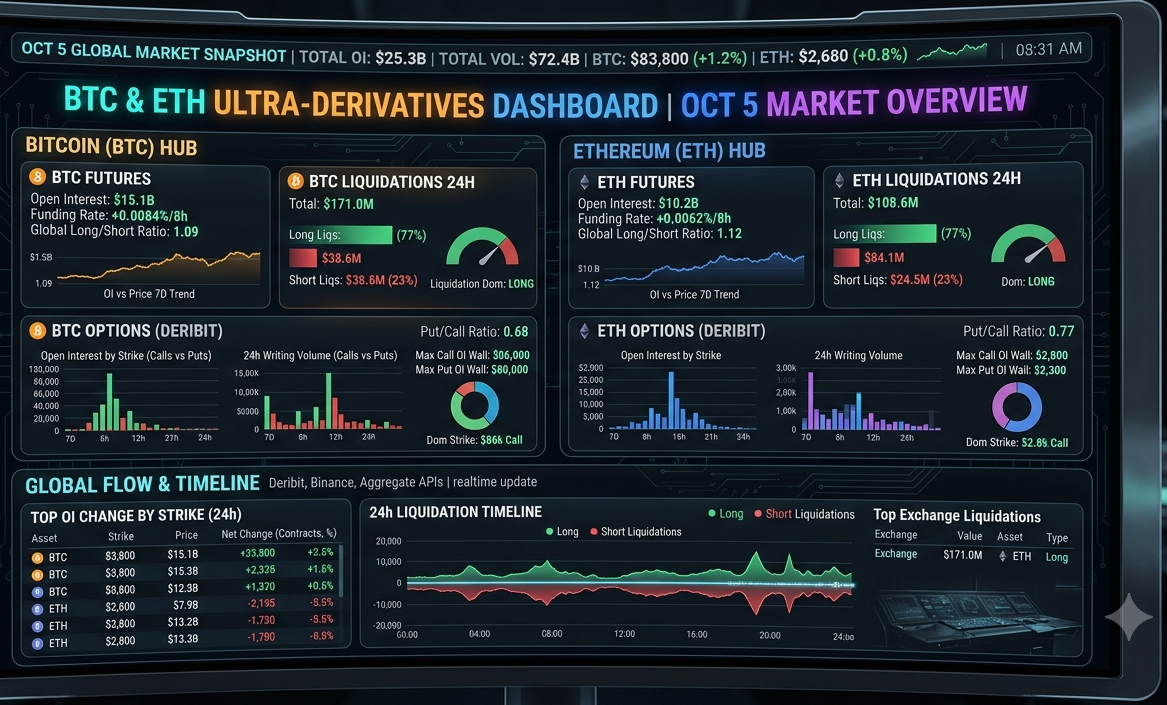
On October 5, 2026, the derivatives market saw a major deleveraging as a liquidation cascade eliminated extreme speculative bullishness. With a total 24-hour volume of $72.4 billion, which surged during the sell-off, aggregated futures open interest dropped to $25.3 billion ($15.1B BTC, $10.2B ETH). Heavily skewed toward long positions, which made up $216.5 million, or 77.4% of all forced liquidations, total liquidations amounted to $279.6 million. This flush effectively reset yearly highs above 18% to +0.0084% (BTC) and +0.0062% (ETH) of perpetual futures funding rates and fixed retail long/short account percentages to 1.07 (BTC) and 1.10 (ETH), therefore eliminating the main structural weakness the market now faces.
Though futures liquidations are fierce, Deribit options data show institutional desks are using volatility suppression to trade inside set ranges. While strong 24-hour call writing volume (58.4% of all written contracts) set firm overhead strike walls at $86,000 (BTC) and $2,800 (ETH), therefore limiting short-term gains, put/call ratios of 0.68 (BTC) and 0.77 (ETH) confirm call dominance. On the other hand, a lot of put open interest supports institutional support floors at $80,000 (BTC) and $2,300 (ETH). Within this $80,000–$86,000 (BTC) range, Deribit dealer gamma stays positive, which means that market makers have to buy dips and sell rallies. This helps to reduce actual volatility unless spot BTC breaks through the important $80,000 put wall floor.







