


 Yen in Focus as BOJ, Fed Rate Hikes Reshape Currency Markets
 XRP Ledger Foundation Confirms 100B Supply Safe After Security Fix
 Bank of America Posts Strong Q4 2024 Results, Shares Rise
 Bank of America Predicts Yen Rebound as USD/JPY Faces Risks
 Mexico's Undervalued Equity Market Offers Long-Term Investment Potential
 RBA Hikes Interest Rate to 4.60% as Inflation Risks Rise
 Morgan Stanley Predicts $10 Trillion RWA Market by 2030
 Most Americans Oppose Election Betting on Prediction Markets, Poll Finds
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 Trump Demands Powell Resign Over Fed Renovation Cost Overruns
 Fed’s Hammack Says Bond Yield Surge Is Not Driven by Inflation Fears
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 Stock Futures Dip as Investors Await Key Payrolls Data
 Cardano Hits Five-Year Transaction Record as ADA Price Falls
 Lithium Market Poised for Recovery Amid Supply Cuts and Rising Demand
 Fed Unveils Stablecoin Rules Under GENIUS Act


 Add as a preferred source on Google
We’ve been neutral in a 0.7130-0.7240 range for Kiwi dollar against US dollar.
NZDUSD in medium term perspectives: The Fed’s tightening cycle plus US fiscal expansion should maintain upside pressure on US interest rates and the US dollar, pushing NZDUSD down to 0.7000 or lower. Granted, the NZ economy is strong and dairy prices have risen, but these forces are subservient to the US dollar’s trend.
We expect NZD to fall through this year, reaching 0.62 at year-end. The support to growth from migration will fade, while the RBNZ -at the very least–are likely to hold rates steady as inflation normalizes, pushing real rates materially lower. The economy is also now subject to credit tightening through numerous channels: macro-prudential constraints, widening mortgage rate spreads, and banks’ discretionary tightening of credit criteria to businesses. We now expect the RBNZ to be on hold this year, but there is a clear downside risk to the OCR in the near term.
Although the Kiwi dollar surged a bit in the recent times but sensing more bearish pressures in the upcoming future especially after data showed that China’s imports surged more than expected but printed lower comparatively with previous period and the greenback remained supported by hawkish US central bank’s tone.
The FOMC remained on hold, which seems momentary, at 0.50%-0.75%. There was little fresh news in the statement that carries hawkish tone - risks are still seen "roughly balanced", activity is expected to expand at a "moderate pace" and that warrants "only gradual increases" in rates.
The Fed conceded that the sentiment surveys have firmed: "Measures of consumer and business sentiment have improved of late" and their confidence on inflation has firmed a touch, the Fed noting: "inflation will rise to 2 pct" (vs "Inflation is expected to rise to 2 pct" previously). Otherwise, current conditions are largely unchanged, job gains are still considered "solid" and activity is growing at a "moderate pace". There are no strong clues here that the Fed is agitating to hike in March.
OTC outlook and hedging framework:
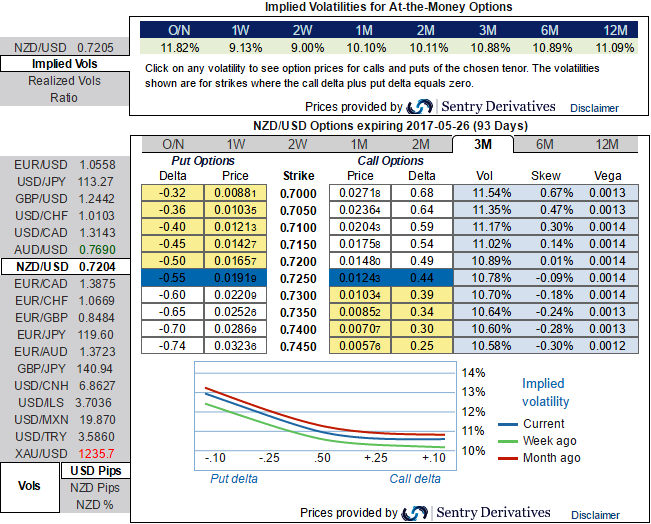
You could notice OTC market discounting these factors in 3m IV skews (they bid for OTM put strikes).
Well, to mitigate the further bearish risks, at spot reference 0.7205 we reckon the NZDUSD options strips with narrowed tenors.
Hence, we advocate initiating longs in 2 lots of 3m -0.49 delta put options, while buying 1 lot of +0.51 delta calls of 1m expiry at net debit.







