


 Fed Unveils Stablecoin Rules Under GENIUS Act
 China Boosts Gold Reserves by 650,000 Ounces as Prices Rally
 RBI Uses $10 Billion Currency Swaps to Drain Excess Rupee Liquidity
 ECB May Stop Rate Hikes After December, Capital Economics Says
 BOJ Flags Import Costs and Yen Shocks as Persistent Inflation Risks
 Global Central Banks Brace for More Rate Hikes as Inflation Risks Rise
 Japanese Yen Retreats as Dollar Rises Ahead of Fed, BOJ Rate Decisions
 BOJ Set for Rate Hike as Inflation and Yen Pressure Mount
 FxWirePro: Daily Commodity Tracker - 21st March, 2022


 Add as a preferred source on Google
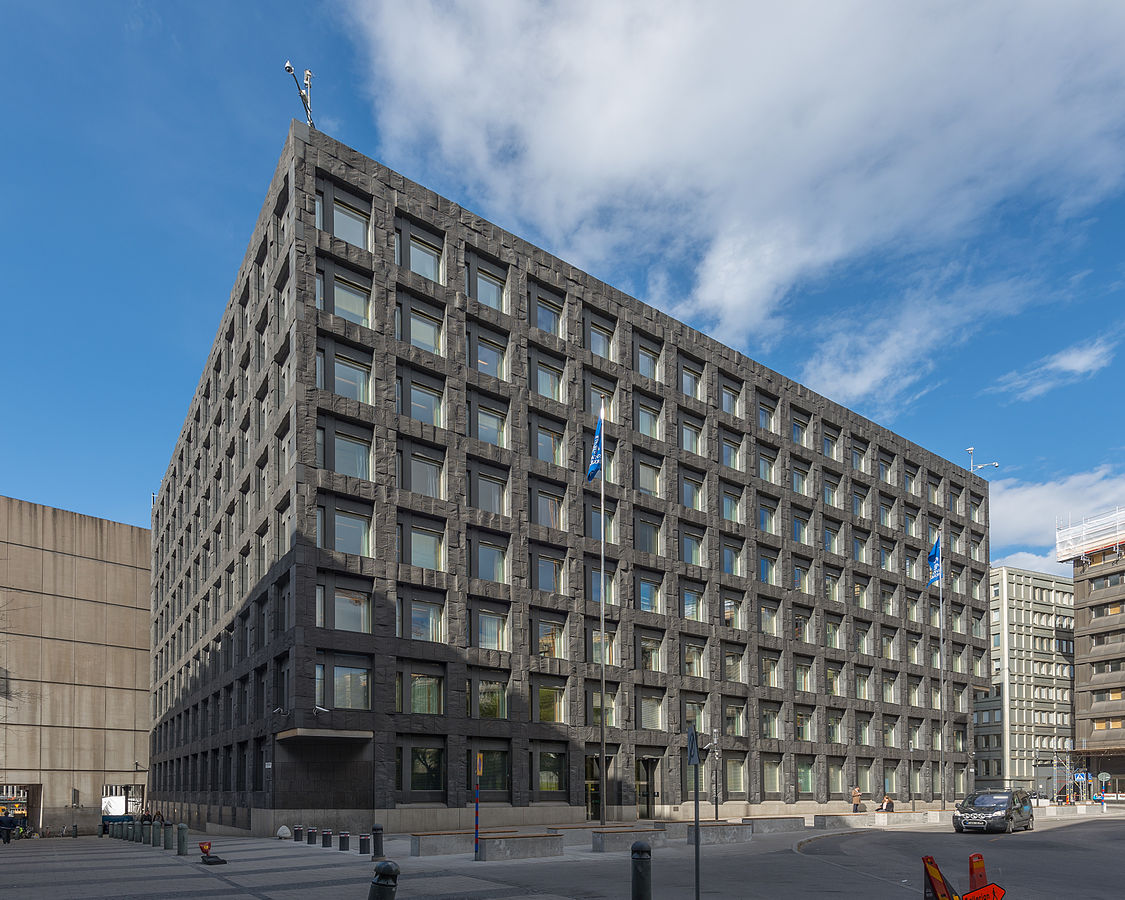
The Riksbank's decision to lower its repo rate further below zero suggested that the central bank is ready to keep aside its concerns regarding strong domestic demand and a housing market bubble in a bid to tackle very low inflation and policy easing by other central banks.
On Thursday, the Riksbank lowered its key interest rate to -0.50% from -0.35%, slightly more than consensus expectation, but on par with Capital Economics forecast. The Executive Board voted 6-2 to ease monetary policy further. However, the majority of the board decided that weak inflation outlook needed more action despite the strong domestic economy. The central bank has revised is headline inflation forecast downward to 0.7% from 1.3% for 2016 and to 2.1% from 2.5% for 2017.
The Riksbank's move seems to have been pre-emptive before the ECB's meeting in March, where it is most likely to further ease policy. According to Riksbank, additional expansionary policy being pursued by other central banks had had an effect on its decision.
Actually, the Swedish central bank still needs to do more to safeguard the delicate upturn in inflation. Sweden's inflation was just +0.1% in December, whereas the CPIF inflation was just +0.9% in December despite the policy rate being negative for one year. Moreover the recent NIER monthly survey of business and consumer inflation expectations one year ahead indicated a renewed drop from 1.9% to 1.8% in January.
Meanwhile, the central bank is correct in worrying about the currency appreciation in the future. There is a strong likelihood that the European Central Bank will lower the deposit rate again and expand its quantitative easing program by more than the current expectations of investors. The Swedish central bank has acknowledged that further measures are required. It has mentioned that it is ready to lower the key rate further, which is seen in its new rate path forecasts.
The Riksbank has to undertake other options. As the korna is trading at a six-month low against the euro at present, it is unlikely that direct FX intervention is imminent. A much likely possibility is certain changes in its bond purchasing program of SEK 200bn.
The central bank has stated that its QE program can be extended by purchasing real and nominal government bonds. However, scarcity problems are still expected to come up, so the best option can be buying foreign currency government bonds, with the added bonus of the krona's depreciation.

- News

- Economy

- Central Banks
- Investing
- Research
- Roundups
- Digital Currency
- Insights
- Technical Analysis
- Technology
- Business
- Law
- Health
- Nature
- Fintech
- Science
- Topic
- Opinions
- ©Econometrics LLC . All Rights Reserved.
Additional measures needed for Riksbank to tackle low inflation
Friday, February 12, 2016 5:39 AM UTC
Editor's Picks



- Market Data
Most Popular




