


 Hong Kong’s Second Solana ETF Launches With Lower Fees
 Bank of America Predicts Yen Rebound as USD/JPY Faces Risks
 RBI Raises Repo Rate to 5.50% in Hawkish Shift on Inflation Risks
 Philippines Current Account Deficit Seen at $19.1 Billion in 2026
 Indonesia Surprises Markets with Interest Rate Cut Amid Currency Pressure
 XRP Price Holds $1.35 Support as Bears Target $1.25
 RBA Says ASX Still Falls Short on Governance and Risk Controls
 Nasdaq Faces Pullback to 26,225 Despite Bullish Outlook, UBS Says
 Ethereum Foundation-Linked Wallets Move $11.13M in ETH to Kraken
 RBI Uses $10 Billion Currency Swaps to Drain Excess Rupee Liquidity
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 Morgan Stanley Predicts $10 Trillion RWA Market by 2030
 Gold Prices Slide as Rate Cut Prospects Diminish; Copper Gains on China Stimulus Hopes


 Add as a preferred source on Google
The Fed unsurprisingly delivered the sixth rate hike in the current cycle. The target range for the federal funds rate is now at 1.50%-1.75%. Considering the recent hawkish turn in Fed communications, markets were more interested in the economic projections of meeting participants. And, indeed, policymakers now see stronger growth and a lower unemployment rate. For 2018, the dot plot still indicates three rate hikes, but the rate path for next year is now somewhat steeper.
The robust US dollar depreciation realized since mid-December seems to have been stopped for now and most recently the US currency was able to regain some lost ground again. There is only one currency in the G10 universe that did considerably well since early February and that is the Japanese yen. JPY’s outperformance for the past three weeks has been remarkable: JPY appreciated to the highest level in 6 months in nominal weighted terms.
If at all USDJPY is projected to slide towards 100 on following driving forces, the below options strategy is advocated on hedging grounds.
A likely by-product of the loss of USD momentum is a pause or even a modest reversal in USD-correlations that have surged this year due to across-the-board dollar weakness. We do not expect any de-correlation to be very pronounced given the primacy of US monetary and fiscal policy in driving FX movements in 1H’18 before other G3 central bank actions assume greater importance later in the year.
Hence ‘hard’ de-coupling option constructs – for instance, dual digitals or worst-of options with out-of-the-money strikes –are not high %age trades in our view despite the attractive implied correlation levels they sell.
Carefully constructed vanilla option triangles can be a viable alternative to exotic options as a mild USD correlation breakdown construct. For instance, one could sell USD puts/JPY calls and USD calls/CAD puts (in equal USD notionals) but hedge out the resultant long CADJPY delta risk by simultaneously buying CAD puts/JPY calls of the appropriate strike (the equivalent cross-yen strike derived from the two USD leg strikes) and in appropriate notional amounts (equal to the yen notional of the USDJPY leg).
Because they involve selling two options and buying one, these triplets entail earning premium at-inception; and because ‘closing the delta loops’ of the triangle leaves little or no directional exposure to begin with, overt spot divergence is not a pre-requisite for retaining the upfront premium credit.
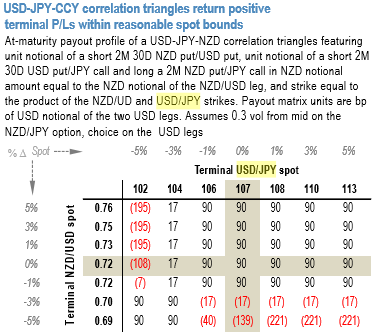
A scenario grid of spot levels at maturity helps visualize terminal payout outcomes; such an exercise for a USD-JPY-NZD triangle for instance shows that returns are positive in most states of world within (subjectively) sensible bounds of terminal spot, not only in the anti-correlated quadrants of the grid but also in significant portions of the rest of the table where traditional de-correlation structures fail (refer above nutshell).
Currency Strength Index: FxWirePro's hourly USD spot index has turned -132 (which is highly bearish), while hourly JPY spot index was at -17 (mildly bearish), NZD is flashing -56 (bearish) and CAD at 71 (bullish) while articulating at 07:35 GMT. For more details on the index, please refer below weblink:
http://www.fxwirepro.com/currencyindex.
FxWirePro launches Absolute Return Managed Program. For more details, visit:







