


 Yen in Focus as BOJ, Fed Rate Hikes Reshape Currency Markets
 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 Moldova Criticizes Russia Amid Transdniestria Energy Crisis
 Fed Minutes Signal Another Rate Hike by Year-End
 US Futures Rise as Investors Eye Earnings, Inflation Data, and Wildfire Impacts
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 Trump Demands Powell Resign Over Fed Renovation Cost Overruns
 Fed’s Hammack Says More Data Needed Before Next Rate Move
 Geopolitical Shocks That Could Reshape Financial Markets in 2025
 US Gas Market Poised for Supercycle: Bernstein Analysts
 BOJ Signals Faster Rate Hikes as Inflation Risks Grow
 Oil Prices Dip Slightly Amid Focus on Russian Sanctions and U.S. Inflation Data
 Stock Futures Dip as Investors Await Key Payrolls Data


 Add as a preferred source on Google
The US continues to lag the growth upgrade cycle, prompting yet another 2% downgrade to the USD TWI forecast. Following some up and down, yesterday was a quiet day for the US currency. The ICE’s USD index traded in a range of 91.75 / 92.10. Even though the data due for publication today, the producer prices (PPI), affect inflation development and thus provide information for the market outlook on the Fed and the USD development we nonetheless do not expect the market to react to the data.
The USD rebound appears to be stalling and if the rally is to gain any further traction, it will need help from the US data (CPI and retail sales data due Thursday and Friday respectively) to give US yields an additional boost and light a fire under Fed Dec rate hike expectations.
On the flip side, SNB is scheduled for its Libor rate announcement on Thursday and you can foresee bearish scenarios of CHF given the fact that SNB resumes FX intervention at higher spot rates than previously and can be bullish if SNB desists from intervention over a multi-month period. Potential trigger events are SNB intervention (weekly sight depos, monthly stats, P&L on Swiss reserves).
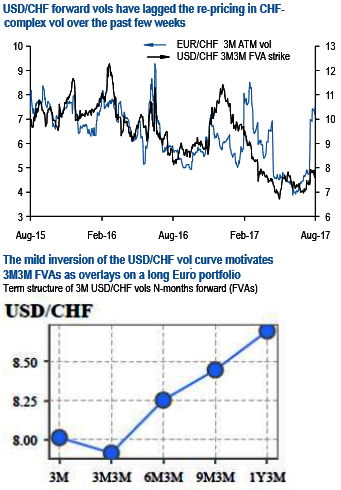
USDCHF 3M3M FVAs have lagged the upturn and are value buys along a mildly inverted curve. Holding USDCHF vol appeals because it can benefit from the full gamut of risk triggers that can afflict all USD-vols, is a useful hedge overlay on a bullish Euro macro portfolio, and retains exposure to idiosyncratic CHF weakness of the kind seen recently, all without the threat of overt SNB management that can frustrate outsized sell-offs in EURCHF.
The FVA format is motivated in part by the fact that USDCHF forward vols have severely lagged the surge in CHF-complex gamma (refer above chart), and partly by the mild inversion of the vol curve that ensures optically appealing flat slide/roll over time (refer above chart).
Admittedly some of the term structure shape is due to the forward starting 3M window covering the quiet holiday weeks of late December (3M3M = mid-November’17 to mid-February'18) that depresses 6M vol, but despite that, it may not be the worst idea to take delivery of and own USDCHF straddles through the first half of December that can reprise the above-average volatility of previous years around ECB and Fed meetings when tapering and rate hike decisions are expected to be announced.







