


 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 AI is supercharging money scams – here’s what you can do to protect yourself
 U.S. Stocks vs. Bonds: Are Diverging Valuations Signaling a Shift?
 US Gas Market Poised for Supercycle: Bernstein Analysts
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 Who should own the knowledge that underpins AI technology?
 Energy Sector Outlook 2025: AI's Role and Market Dynamics
 fnny Beta Launches With a Simple Idea: Find an Event, Show Up, Get Rewarded
 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays


 Add as a preferred source on Google
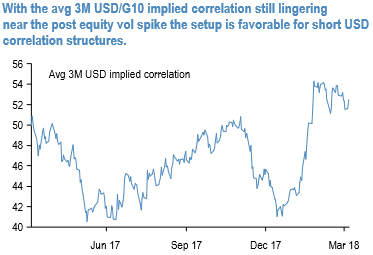
The lack of many reactions from the likes of Antipodeans and loonie fetches out prospects to buy underpriced hedges via optionality. Most noticeably, aggregate USD-denominated implied correlations still trade near their highs from around the VIX shock (refer 1st chart) – a set-up that is favorable for betting on the divergence between reserve and high beta currencies via short USD correlation structures.
1x2 forward volatility (FVA) spreads utilize favorable vol slide along term structures and are passage-of-time friendly, low maintenance long vega positions.
The basic construct involves selling a shorter dated FVA along the upward sloping segment of the vol curve to partially fund the purchase of a longer dated FVA along a flatter part of the term structure.
The roll-down of the short leg compensates (or even eliminates) the slide of the long position while preserving the overall net long vol exposure of the structure. Historically P/L on this type of structures closely coincided with bounces in the spread pricing (see 2nd chart).
In the case of EUR/Antipodean crosses, current entry levels near pre GFC lows are a bargain by historical standards(refer 3rd chart), while the net 6 months static vol slide at forward start of the short leg is substantially positive (+1vol), making the long/short structure superior to holding a similar expiry straddle.
FxWirePro launches Absolute Return Managed Program. For more details, visit:







