


 Asian Stocks Fall as Bond Yields Surge Ahead of Trump-Xi Summit
 Oil Prices Surge as U.S.-Iran Diplomacy Hopes Fade
 Oil Prices Ease as Iran Tensions Clash With Diplomacy Hopes
 RBI Uses $10 Billion Currency Swaps to Drain Excess Rupee Liquidity
 Oil Prices Jump 3% as Houthi Attack Revives Supply Fears
 Wall Street Falls as Treasury Yields Surge, Oil Rebounds on Iran Tensions
 South Korea, US Discuss Warship Building Cooperation
 US, China Extend Trade Truce to Jan. 10 Ahead of Trump-Xi Summit
 Fed Unveils Stablecoin Rules Under GENIUS Act
 Mexico-US Trade Talks Delayed to October as Tariff Negotiations Continue
 China’s ‘Lipstick King’ Says AI Won’t Replace Livestream Hosts
 Soybean Futures Slip as Traders Await Trump-Xi Trade Signals
 European Stocks Fall as Bond Yields and Geopolitical Risks Weigh
 US 10-Year Treasury Yield at 6% Emerges as New Market Risk Threshold
 Wall Street Ends Flat as Oil, Treasury Yields and Fed Jitters Rattle Markets
 Dollar Holds Near Two-Month High as Yen Approaches 160
 U.S. 10-Year Treasury Yield Hits 2007 High as Fed Rate Hike Bets Rise


 Add as a preferred source on Google
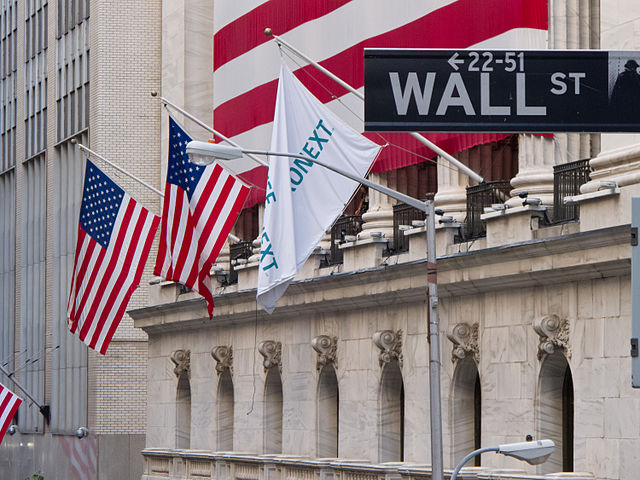
U.S. stocks finished mixed on Tuesday as investors reacted to weaker-than-expected retail sales data and positioned cautiously ahead of a highly anticipated labor market report. The Dow Jones Industrial Average edged higher to notch its third consecutive record close, while the S&P 500 and Nasdaq Composite ended the session lower amid pressure on technology and communication services stocks.
The S&P 500’s communication services sector was the weakest performer of the day, dragged down largely by Alphabet. Shares of Google’s parent company slid 1.8% after it announced a $20 billion bond sale. The move reignited investor concerns about rising capital expenditures among major technology firms as they race to dominate the artificial intelligence market. Amazon, Alphabet, Meta Platforms, and Microsoft are collectively expected to spend hundreds of billions of dollars by 2026 to support AI infrastructure and development.
Broader market sentiment was also dampened by U.S. retail sales data showing no growth in December, defying economists’ expectations for a 0.4% increase. The slowdown was driven by reduced spending on vehicles and other big-ticket items, signaling that consumer demand and economic momentum may be cooling as the new year begins.
Despite the soft data, hopes for a more dovish Federal Reserve gained traction. According to CME Group’s FedWatch tool, the probability of a rate cut in April rose to 36.9%, up from 32.2% a day earlier. Markets still largely expect the Fed to hold rates steady until June, when Kevin Warsh, President Donald Trump’s nominee for Fed chair, could assume the role pending Senate approval.
Rate-sensitive sectors such as utilities and real estate outperformed, benefiting from the “bad news is good news” narrative tied to lower interest rate expectations. However, investors remained cautious ahead of the delayed nonfarm payrolls report, which could significantly influence market direction.
The Dow rose 52.27 points to 50,188.14, the S&P 500 fell 0.33% to 6,941.81, and the Nasdaq declined 0.59% to 23,102.47. Individual stocks saw sharp moves, with Datadog surging nearly 14% on strong earnings, Spotify jumping almost 15% on upbeat guidance, and S&P Global tumbling nearly 10% after issuing a weak profit forecast.







