


 Moldova Criticizes Russia Amid Transdniestria Energy Crisis
 Energy Sector Outlook 2025: AI's Role and Market Dynamics
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 RBA Says ASX Still Falls Short on Governance and Risk Controls
 RBI Rate Hike Bets Surge as Inflation Rises
 BOJ Signals Faster Rate Hikes as Inflation Risks Grow
 Urban studies: Doing research when every city is different
 Stock Futures Dip as Investors Await Key Payrolls Data
 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 Visa Wins China Approval to Prepare Domestic Payments Expansion
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 Fed’s Williams Signals One More Rate Hike Before Year-End
 Bitcoin Price Drops as US Dollar Hits 18-Month High
 European Stocks Rally on Chinese Growth and Mining Merger Speculation
 Morgan Stanley Predicts $10 Trillion RWA Market by 2030
 DeFi Development Adds 22,070 SOL to Solana Treasury


 Add as a preferred source on Google
A glimpse through fundamentals: ECB monetary policy will be on autopilot in the near future and thus diminish in importance as a driver for the euro in the coming weeks, leaving the currency open to vagaries of other factors such as US-dynamics, which are more dollar bullish at the moment (a substantially better-than expected US GDP outcome this week reinforces strong growth momentum for the dollar).
The Federal Reserve last night left interest rates unchanged at 1-1.25%, as expected. There was no press conference or update of economic forecasts. The press statement was largely unchanged: it sounded a little more upbeat about recent economic developments, while still acknowledging some concerns about low inflation. A December US rate rise is still likely, even though it was not explicitly signalled. Separately, President Trump is due to announce the next Fed Chair at 19:00GMT. His pick is expected to be Jerome Powell, who is a current Fed Governor, and would represent continuity in monetary policy. Powell is scheduled to speak at an event today.
Thus a monetary policy catalyst for euro strengthening will be lacking in the near-term. Instead, US-specific factors will dominate in the near-term.
Moreover, the Euro area political risks which will likely become more negative into Q1 given Italian elections. The longer-term view is still euro bullish since focus will eventually shift to ECB rate hikes (Sep’18) EURUSD target is at 1.25.
But the near-term outlook is more fragile given the factors outlined above, in combination with crowded EUR longs and EURUSD overshooting rate differentials on most frameworks (chart 3).
Options strategy: Buy EURUSD 2m put spread, strikes 1.1450/1.1350 Indicative offer: 0.18% (spot ref 1.1649000).
Max leverage: 5.6x, the short put finances half of the cost.
The maximum payout at expiry (the strikes’ difference captures one figure) at and below 1.1350 is more than five times the premium.
Rationale: Euro at risk of a deeper correction, ECB is in autopilot mode, having mentioned that, following last week’s ECB dovish communication, the softer euro triggered a massive selloff in the EURUSD vol market.
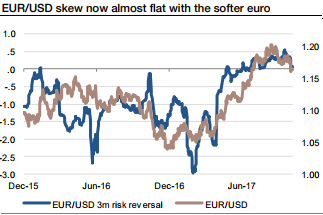
Both volatilities and risk reversals (RR) are under significant selling pressure, with the front-end of the implied vol curve returning to its summer lows (the sub 3m segment is trading below 7), and short-dated RR trading at nearly flat levels.
However, the short-dated skew did not turn negative, leaving OTM short-dated euro puts still a cheap hedge if all the pieces are in place for a deeper correction.
Risk profiling: Limited to the premium, as the trade is intended to be a hedge, investors buying this standard put spread structure cannot lose more than the premium initially paid.







