


 Navigating the Crypto Pulse: Weekly Market Resilience and Institutional Inflows
 Hong Kong’s Second Solana ETF Launches With Lower Fees
 European Stocks Rally on Chinese Growth and Mining Merger Speculation
 Fed’s Williams Signals One More Rate Hike Before Year-End
 XRP Price Holds $1.35 Support as Bears Target $1.25
 XRP Ledger Foundation Confirms 100B Supply Safe After Security Fix
 Fed’s Hammack Says Bond Yield Surge Is Not Driven by Inflation Fears
 Bitcoin ETFs Lose $681 Million, Ending Three-Week Inflow Streak
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 Cardano Hits Five-Year Transaction Record as ADA Price Falls
 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 RBI Uses $10 Billion Currency Swaps to Drain Excess Rupee Liquidity
 BNB Price Faces Pressure as DOJ Investigates Binance
 Indonesia Surprises Markets with Interest Rate Cut Amid Currency Pressure
 Wall Street Analysts Weigh in on Latest NFP Data


 Add as a preferred source on Google
Bearish sterling scenarios:
1) The UK growth slows below 1% as consumers are squeezed by inflation and falling house prices.
2) Outright capital repatriation from slower moving long-term investors including central banks.
3) Initial Brexit talks flounder on the size of the UK's exit-bill.
Bullish Sterling scenarios:
1) The govt pursues a lengthy transitional deal with the EU which maintains the trade status quo for 2-3 years.
2) The economy rebounds to 2.0-2.5%.
3) 2-3 MPC members dissent for tighter policy at the Aug MPC/QIR,
4) Current a/c deficit shrinks below 2%.
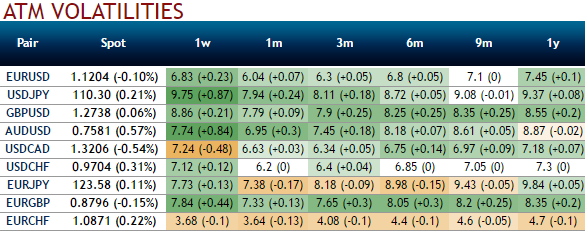
Snap rallies and add gamma puts bidding mounting RR and skews to hedge GBPUSD:
Please note that the nutshell above showing the positive shift in delta risk reversals of GBP has to be fairly interpreted, net risk reversals have still been indicating downside risks but interim rallies in the weeks to come.
While spiking IVs on a higher side of longer tenors with positively skewed IVs still signify the hedgers’ interest for OTM put strikes.
Mounting negative delta risk reversal can be interpreted as the opportunity for put longs as the market reckons the price has downside potential for large movement in the days to come which is resulting option holders’ on competitive advantage.
Hence, we advocate weighing up above aspects in below option strategy, we eye on loading up with fresh vega longs for long-term hedging, more number of longs comprising of ATM instruments and ITM shorts in short term would optimize the strategy.
The aggressive volatility investors want to capture GBP should consider buying ATM put instruments and/or being long of the smile convexity, against ATM volatility.
Further GBPJPY weakness and/or abrupt upswings suggest building a directional and volatility patterns at the same time: the value of OTM puts would likely to rise significantly as the IVs seem to be favoring these distant strikes. We, therefore, recommend shorting 2w IVs and buying IV skews of 2m tenors.
As a result, we believe in jacking up in long leg of the below option strategy:
Initiate longs of 2 lots of 2m at the money gamma put options, simultaneously, short 1 lot of (1%) out of the money put of 2w expiry with positive theta. It is advisable to prefer European style options.
We’ve chosen Gamma instruments on long leg because Gamma is the rate of change of the Delta with respect to the movement of the rate in the underlying spot FX market. In the Sensitivity table, Gamma shows how much the Delta will change if the underlying rate moves by 1%, thus the hedger would be in a position to ascertain how much of his FX exposure is effectively hedged.







