


 Oil Prices Mixed as Russia Diesel Deal and Houthi Attacks Raise Supply Concerns
 Fed’s Williams Signals One More Rate Hike Before Year-End
 Arthur Hayes Announces FLOP Testnet Launch Within Weeks
 Australia Consumer Confidence Plunges as RBA Rate Hike Hits Households
 Cardano Price Drops 15% as Whales Sell 110 Million ADA
 Gold Prices Rebound as Dollar Weakens Ahead of US Inflation Data
 IMF Maintains 2027 Global Growth Forecast at 3.4% Amid Rising Risks
 UK Finance Minister Healey Calls for Fiscal Discipline Amid Global Risks
 Nasdaq Falls as Oil Prices Surge Ahead of Bank Earnings
 ECB May Stop Rate Hikes After December, Capital Economics Says
 Gold's Tug-of-War: Geopolitical De-escalation Fights Falling Yields as Markets Eye US CPI
 BOJ Signals Faster Rate Hikes as Inflation Risks Grow


 Add as a preferred source on Google
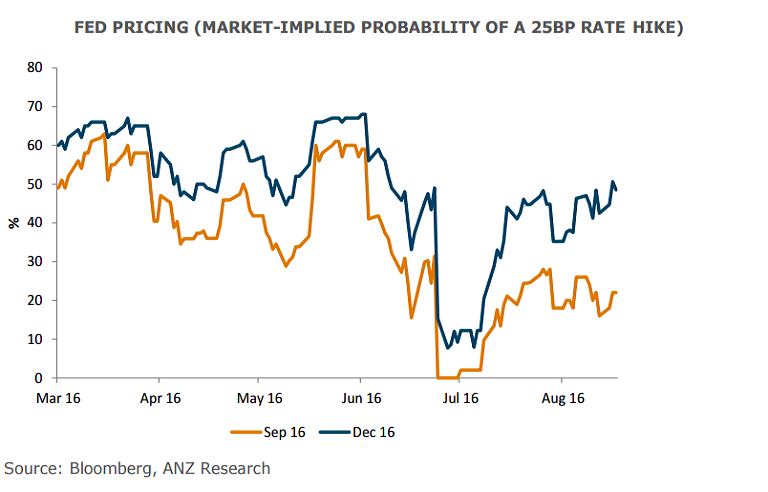
US Federal Open Market Committee minutes released overnight highlight that officials are divided, with no clear indication of when the central bank will hike next. The minutes showed that members were generally upbeat about the economic outlook and labor market, but several said a slowdown in the future pace of hiring would argue against a near-term hike. The market currently is 22 percent priced for a move in September and just under 50 percent for December.
Fed officials have recently reminded the market not to be too complacent and that the bias at the Fed is still to raise interest rates. NY Fed president Dudley’s said on Tuesday that markets are too complacent about rate hike risks. Dudley said he expected stronger growth in the US in H2 than in H1 and further improvement in the labour market. That sentiment was echoed by FRB Atlanta President Lockhart.
“Hawks balanced with doves and the Fed in wait-and-see mode,” said Kit Juckes, strategist at Societe Generale. “I don’t think this tells us much about the September meeting, which is, as ever, data- and market-dependant, but it does tell us that the most we’ll get is a very slow and cautious tightening path.”
The key to when the central bank moves remains the underlying data flow. Recent data suggest growth probably accelerated in Q3. Headline Q2 GDP growth (+1.2 percent saar) was disappointing, but underlying activity was still positive and will remain supported by stimulatory financial conditions. Residential investment, which was a significant drag on Q2 GDP appears to be recovering. Recent solid gains in employment suggest underlying momentum is better than the headline GDP.
That said, despite signs of a pickup in wage growth, headline inflation remains below target. July CPI fell to 0.8 percent y/y from 1.0 percent in June and the PCE is hovering at 0.9 percent y/y. Core inflation is closer to the Fed’s 2 percent target. University of Michigan 5-10yr inflation expectation remains low but stable at 2.6 in July.
"An ongoing tightening in the labour market and relatively stable inflation expectations point to a gradual return in headline (PCE) inflation towards the target (2 percent) over the near to medium term," said ANZ in a report to its clients.
The FOMC's next meet (21-22 Sept) will be accompanied by a press conference from Janet Yellen and the updated Summary of Economic projections (including the fed fund rate). Hurdle probably remains a little high for September rate move. Another round of monthly data (employment and CPI) will be available for scrutiny. However, one month of data may not be sufficient to provide the confidence the Fed needs.
The dollar saw choppy trading, shorter-term Treasury prices turned higher and stocks nudged into positive territory after the release of minutes on Wednesday. DXY extending dips on the day, down 0.36 percent at 94.39 at 11:30 GMT. USD/JPY was at 100.19 while EUR/USD was at 1.1327.







