


 Yen in Focus as BOJ, Fed Rate Hikes Reshape Currency Markets
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 Moldova Criticizes Russia Amid Transdniestria Energy Crisis
 2025 Market Outlook: Key January Events to Watch
 BOJ Signals Faster Rate Hikes as Inflation Risks Grow
 Geopolitical Shocks That Could Reshape Financial Markets in 2025
 BlackRock’s Rick Rieder Favors Bonds Over Stocks as Treasury Yields Surge
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 Oil Prices Dip Slightly Amid Focus on Russian Sanctions and U.S. Inflation Data
 Energy Sector Outlook 2025: AI's Role and Market Dynamics
 Japanese Yen Retreats as Dollar Rises Ahead of Fed, BOJ Rate Decisions
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 RBA Says ASX Still Falls Short on Governance and Risk Controls
 Wall Street Analysts Weigh in on Latest NFP Data


 Add as a preferred source on Google
Bearish EURGBP Scenarios:
1) European growth fails to lift above 1%.
2) Stalemate in the UK-EU Brexit trade talks, which increases the risk of a no-deal exit at the end of 2020.
3) The UK government announces a much more stimulatory budget in March (the manifesto envisaged fiscal thrust of 0.4-ppt for 2020 and nothing thereafter).
4) Johnson eventually acknowledges the need for a lengthier transition period.
5) The UK government softens its stance and agrees to closer regulatory alignment to maintain frictionless trade.
Bullish EURGBP Scenarios:
1) A more substantive loosening in German fiscal policy.
2) The BoE cuts rates in January or March
3) The UK economy fails to rebound after the election.
4) A lengthy extension to the Brexit transition period beyond end-2020.
5) A re-acceleration of CB demand for EUR, potentially linked to #2 and #3.
6) Johnson refuses to soften his trade stance, leading to an even greater risk of a no deal exit at the end of 2020.
Along with the easing in global trade tensions provides strong justification for the BoE keeping interest rates unchanged at 0.75% at this juncture. However, following dovish comments from a number of MPC members recently, today’s outcome is viewed by the market as 50/50, while a full 25bp cut is priced by May. While we believe it more likely than not that the MPC keep rates unchanged, we also doubt that the message from the Committee will be sufficiently strong to alter meaningfully the market’s belief that a rate cut may be forthcoming in the near term.
Hence, our defensive stance in EURGBP has been dictated by the receding global economic tide, but we cannot ignore that political risk has been an instrumental factor in these worse macro outturns. This warrants a tactical reduction in our defensive exposure but we uphold our hedging portfolios via 3-way straddles.
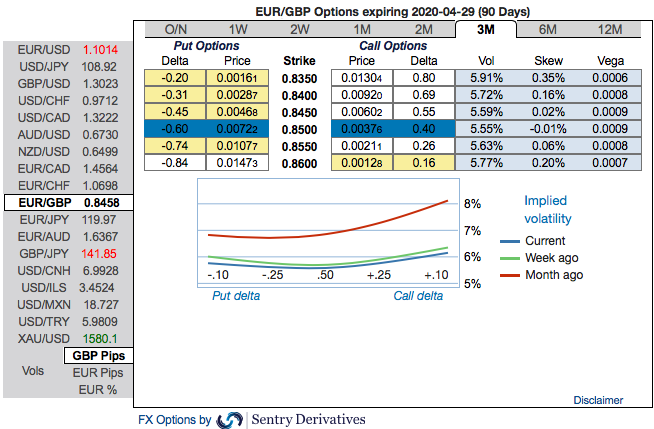
The passively skewed IVs of 3m tenors are well-balanced, indicating both upside and downside risks, more bids are observed for OTM call strikes up to 0.8350 level.
While EURGBP risk reversals of the existing bullish setup remain intact despite fresh bids for bearish risks in the short-term tenors. Below options strategy could be deployed amid the expected turbulent conditions. According to the OTC FX surface, 3-way options straddle versus ITM calls seem to be the most suitable strategy for EURGBP contemplating some OTC sentiments and geopolitical aspects.
Options Strategy: The strategy comprises of at the money +0.51 delta call and at the money -0.49 delta put options of 3m tenors, simultaneously, short (1%) ITM put option of 1m tenors. The strategy could be executed at net debit but with a reduced trading cost.
Hence, on hedging as well as trading grounds, initiate above positions with a view of arresting potential FX risks on either side but slightly favoring short-term bearish risks. Courtesy: Sentry, Saxo & JPM







