


 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 European Stocks Rally on Chinese Growth and Mining Merger Speculation
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 U.S. Banks Report Strong Q4 Profits Amid Investment Banking Surge
 Indonesia Surprises Markets with Interest Rate Cut Amid Currency Pressure
 Bank of America Posts Strong Q4 2024 Results, Shares Rise
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 Hawkish Fed Fuels Gold Sell-off: Gold Dives Below $4300 Amidst Rate Hike Fears
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 US Gas Market Poised for Supercycle: Bernstein Analysts


 Add as a preferred source on Google
There is a late swing in the Italian opinion polls in favour of MS5. While holding forecasts unchanged, we have established a decent long EUR position in the macro portfolio (vs JPY, NZD, and an EURUSD proxy).
The concerns about the Italian elections mount in 1Q’18 that poses bullish risks to the Swiss franc. While the election frontrunner Matteo Salvini said his party is ready to withdraw from the European Union and the Eurozone unless Brussels stops "victimizing" Italy with harsh economic demands.
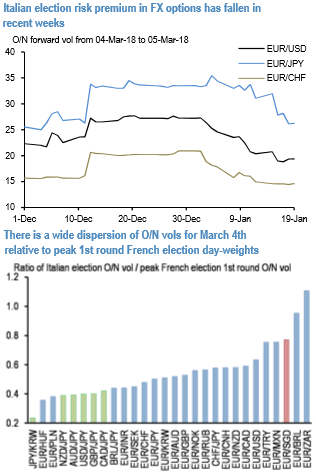
Italian election risk premia have continued to slide this year (refer above diagram), and yen-crosses, in particular, have been the largest casualties of the re-pricing.
At current levels, 4th March O/N vol levels in JPYKRW (8.7), AUDJPY (14.2), USDJPY (11.1), GBPJPY (13.7) and CADJPY (13.7) all look unthreatening, especially when compared to the frenzy of the French election episode (refer above diagram).
On average, options markets are priced at 50% of the event premium of the 1st round of the French vote from last year which is perhaps fair on the whole, but there is significant dispersion across currencies that creates the potential for relative value:
JPY crosses are at the cheap end of the spectrum with an average French election O/N multiple of 0.4.







