


 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 Gold's Tug-of-War: Geopolitical De-escalation Fights Falling Yields as Markets Eye US CPI
 Crypto Derivatives Dashboard: Bulls Retain Control Amid $488M Liquidation Flush
 Morgan Stanley Predicts $10 Trillion RWA Market by 2030
 Gold Prices Slide as Rate Cut Prospects Diminish; Copper Gains on China Stimulus Hopes
 Philippines Current Account Deficit Seen at $19.1 Billion in 2026
 Trump Demands Powell Resign Over Fed Renovation Cost Overruns
 Ethereum Foundation-Linked Wallets Move $11.13M in ETH to Kraken
 Navigating the Crypto Pulse: Weekly Market Resilience and Institutional Inflows
 Fed’s Williams Signals One More Rate Hike Before Year-End
 Ripple-Backed Evernorth Set for Nasdaq Debut With 473 Million XRP
 Visa Wins China Approval to Prepare Domestic Payments Expansion
 Hyperliquid (HYPE) Price Analysis: Can Bulls Push Above $88?
 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 Fed Unveils Stablecoin Rules Under GENIUS Act


 Add as a preferred source on Google
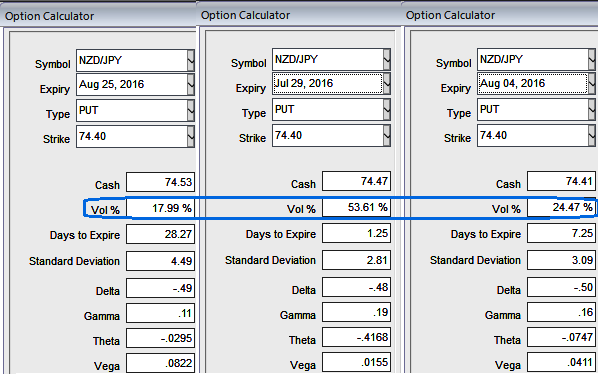
The implied volatilities of ATM contracts for near month expiries of this the pair are spiking in sky-rocketed pace. Here are the evidences:
ATM IVs of this pair is trending higher at around 53.61%, 17.99% and 24.47% for 1D, 1M and 1W expiries respectively which is the highest among G20 currency space. While current IVs of ATM contracts are at highest levels which seem quite absurd but likely to perceive hover around at an average 18% in the long run that would divulge pair’s gain contemplating risk reversal arrangements.
We give the absolute credits of the rising IVs to monetary policy season, as Yen remains fairly well bid against Kiwi despite the BoJ’s upbeat assessment of the Japan economy and deflationary pressures from decades together.
This week is a busy one for Japan data watchers with many June releases including CPI, housing starts, and FX markets digesting the better than forecasted trade balance data, while the key focus should be on Friday’s BoJ policy meeting.
With a clear slowing in the inflation trend and inflation expectations among both corporates and households, and Brexit, we find it hard to imagine whether the BoJ would ease this week or not, given its frequent statement “the central bank would observe risks to economic activity and prices, and take easing measures in terms of three dimensions—quantity, quality, and the interest rate.
The economy has struggled with deflation for two decades. Even after the BOJ's massive qualitative and quantitative easing (QQE) program and venture into negative interest rates territory, the Asian economy hasn't been able to boost domestic consumption and shake off deflation.
Indeed, according to the Japan Center of Economic Research, 86% of 42 economists surveyed between June 27 and July 4 expect policy easing next week. No action by the BoJ would erode its credibility on achieving the inflation target and tighten monetary conditions through JPY appreciation.
Whereas an OCR cut by RBNZ is all on the table but seems fully priced in for next month as the major contributor of Kiwis growth the GDT price index has shown a remarkable improvement has sent an earlier confirmation of easing bias, but FX markets remain reluctant to get short in Kiwi dollar.
NZDJPY’s rising implied volatility could be used as follows in option strategies:
Trading implied volatility directionally (vega)
Capturing the volatility risk premium in trading the gamma (dynamic delta-hedging)
Trading the volatility market (smile and term structure dynamics) non-directionally.







