


 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 Indonesia Surprises Markets with Interest Rate Cut Amid Currency Pressure
 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 2025 Market Outlook: Key January Events to Watch
 U.S. Stocks vs. Bonds: Are Diverging Valuations Signaling a Shift?
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 Fed’s Williams Signals One More Rate Hike Before Year-End
 Fed Unveils Stablecoin Rules Under GENIUS Act
 European Stocks Rally on Chinese Growth and Mining Merger Speculation
 BOJ Signals Faster Rate Hikes as Inflation Risks Grow
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 Philippines Current Account Deficit Seen at $19.1 Billion in 2026
 UBS Predicts Potential Fed Rate Cut Amid Strong US Economic Data


 Add as a preferred source on Google
Japanese real exports fell in December but finished Q4 with a strong gain.
January flash manufacturing PMI for Japan edged up further; future output index signals a favorable outlook.
Japanese core CPI deflation continued through December, but inflation likely would be back in January.
The Cabinet Office’s new estimate of Japan’s potential growth rate is 0.8%, the output gap is less than 0.5%-pt.
BoJ monetary policy meeting did not add any uncertainty to the FX markets as they maintained status quo in bank rates, Japan’s preliminary GDP Q/Q, IP report, consumption and labor market indicators are scheduled for the week, while CPI and manufacturing production prints from UK’s perspectives are also scheduled for this week.
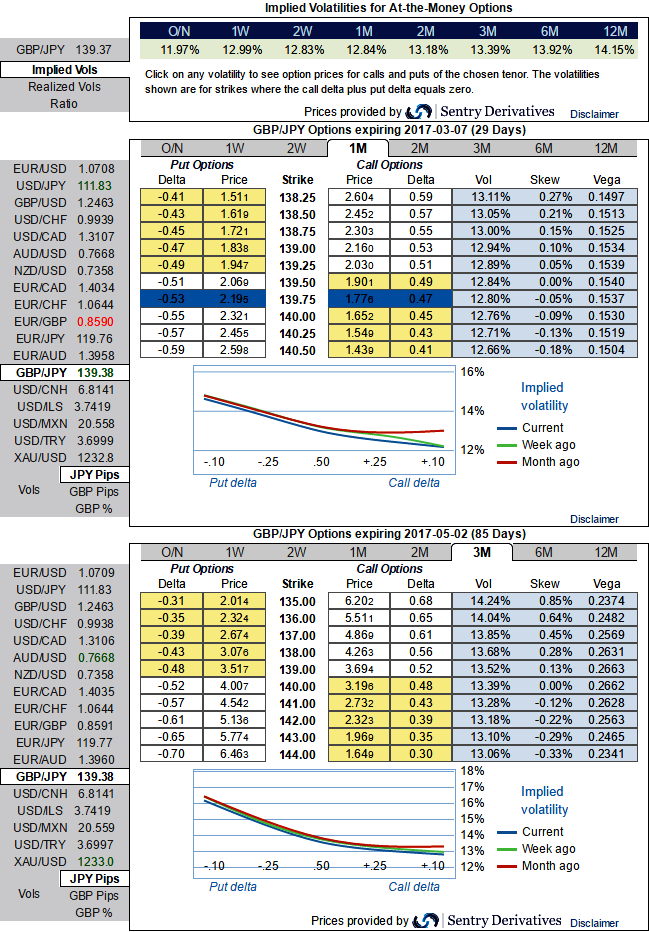
Despite GBPJPY downtrend seems to be intact, a lot of bad news is already priced in and digested by the market, preventing it from being overly bearish. Brexit caused two Sterling debacles, first in June with the vote and then after the summer when PM May suggested a hard exit. Cable lost almost about 15% over a quarter and it now seems the dust has settled. In the process, volatility fell but remained relatively high on a historical basis. Assuming a medium-term range in cable and that negative surprises are no longer market tail risks, the GBP volatility is still a short.
Hence, even if the aggressive volatility investors wants to capture GBP should consider buying ATM put instruments and/or being long of the smile convexity, against ATM volatility. But further GBPJPY weakness and/or abrupt upswings suggests building a directional and volatility patterns at the same time: the value of OTM puts would unlikely to rise significantly as the IVs do not seem to be favoring these distant strikes. We, therefore, recommend buying a 3m IV skews and risk reversal with ATM options.
Option Trade Recommendation:
In order to match above IV skewness for 1-3m tenors, we advocate initiating longs in 2 lots of 3m ATM -0.49 delta puts, while long in 1 lot of +0.51 delta call of 1m tenor, please be noted that the payoff function of the strategy likely to derive positive cashflows regardless of swings but more potential from 2 puts are more than 1 call.
The risk is limited to the extent of the price paid to buy the options.
The reward is unlimited till the expiry of the option.
Please note that the trader can still make money even if his anticipation goes wrong – but the spot FX has to move in the opposite direction really fast. The 1 call bought has to beat the cost of buying all the options and still bring in some profits.







