


 XRP Ledger Foundation Confirms 100B Supply Safe After Security Fix
 Cardano Hits Five-Year Transaction Record as ADA Price Falls
 RBA Says ASX Still Falls Short on Governance and Risk Controls
 Arthur Hayes Announces FLOP Testnet Launch Within Weeks
 Visa Wins China Approval to Prepare Domestic Payments Expansion
 Philippines Current Account Deficit Seen at $19.1 Billion in 2026
 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 Wall Street Analysts Weigh in on Latest NFP Data
 Ethereum Foundation-Linked Wallets Move $11.13M in ETH to Kraken
 2025 Market Outlook: Key January Events to Watch
 NEAR Price Surges 11% as Trading Volume Doubles
 UBS Predicts Potential Fed Rate Cut Amid Strong US Economic Data
 Dogecoin Price Rises as Bitwise Plans DOGE ETF Closure
 Fed Minutes Signal Another Rate Hike by Year-End
 Fed Unveils Stablecoin Rules Under GENIUS Act


 Add as a preferred source on Google
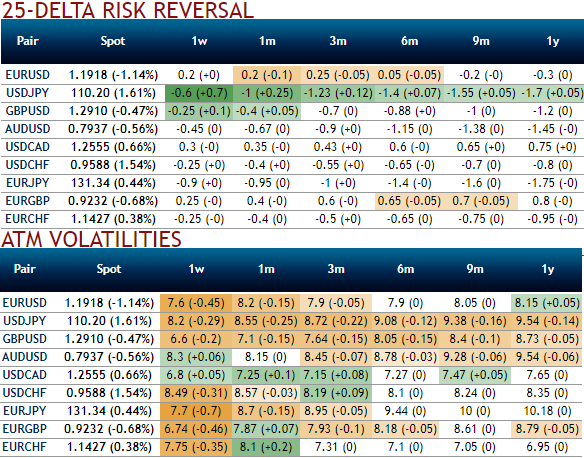
Please be noted that the implied vols of euro crosses have been shrinking lower in spite of the series of data flows are lined up.
German retail sales (actual -1.2% versus consensus -0.5% and previous 1.1%), German and Italian unemployment claims, Euro area unemployment and inflation numbers are due to be announced shortly.
EUR vols and bearish neutral risk reversals remain low compared to the level of rates. Also, in longer tails, the EUR volatility smile remains flat compared with the rates vs vol correlation seen since 2015 and over the past week.
The steepness of the EURJPY risk-reversal curve renders back-end tenors better shorts, risk reversals have been bearish neutral. While positively skewed IVs towards OTM put strikes signifies hedgers’ bearish sentiments but puzzles prevailing uptrend of euro.
However, we prefer sticking to 2017 expiries (6M) since 2018 dates come with unpredictable Italian election risk. The EUR/gold risk-reversal curve is much flatter in comparison hence short tenors work fine. We enter short 6M 25D EURJPY risk-reversals (delta-hedged).
We advocate maintaining the bullish exposure in EURJPY via a call RKO as JPY weakening is likely to be a slow grind rather than explosive.
Sell 6M EUR/JPY 25D risk-reversal (buy EUR calls - sell EUR puts), delta-hedged.
Vol pts Positive smile theta participation in Euro bull-trend.
The macro theme of euro area leading outperformance remains dominant; maintain core EUR or proxy longs as growth and inflation data continue to be supportive. Accordingly, encourage long EUR vs in cash (vs USD) and through options in EURJPY (131 call, RKO 135).
Any spot holdings, wise to book returns in long EURJPY cash; but stay long EURJPY in options structure.
A key judgment call in G10 is to separate those central banks that have the potential to change policy in the near term from those that are unlikely to do so. The BoJ is firmly in the latter bucket and its yield targeting framework have left JPY as having the highest beta of any other currency to DM yields.
The short JPY leg of these trades has thus been motivated by its sensitivity to higher yields. We still recommend keeping exposure to long EURJPY trades but think that the move will likely be a grind higher rather than an explosive move that one might expect if the Fed weren’t on the side lines and US yields were moving higher as well. Thus we take profits on the cash version and keep exposure through the EURJPY call RKO to participate in the dubious bull run.
Currency Strength Index: FxWirePro's hourly EUR spot index is flashing 79 (which is bullish), while hourly JPY spot index was at -63 (bearish) at 07:00 GMT. For more details on the index, please refer below weblink:
http://www.fxwirepro.com/currencyindex.
FxWirePro launches Absolute Return Managed Program. For more details, visit:







