


 South Korea, US Discuss Warship Building Cooperation
 BOJ Set for 25-Basis-Point Rate Hike as Yen Weakness Fuels Inflation
 Japan Private-Sector Growth Slows as Domestic Demand Weakens
 BOJ Flags Import Costs and Yen Shocks as Persistent Inflation Risks
 Fed Unveils Stablecoin Rules Under GENIUS Act
 China’s ‘Lipstick King’ Says AI Won’t Replace Livestream Hosts
 Russian Envoy Dmitriev Heads to US for Ukraine Talks
 Oil Prices Jump 3% as Houthi Attack Revives Supply Fears
 Dollar Holds Near Two-Month High as Yen Approaches 160
 Asian Currencies Mixed as Dollar Holds Near Two-Month High
 JPMorgan Sees ECB Raising Rates to 2.75% in December
 Dollar Falls as Oil Eases, Yen Jumps on Intervention Signals


 Add as a preferred source on Google
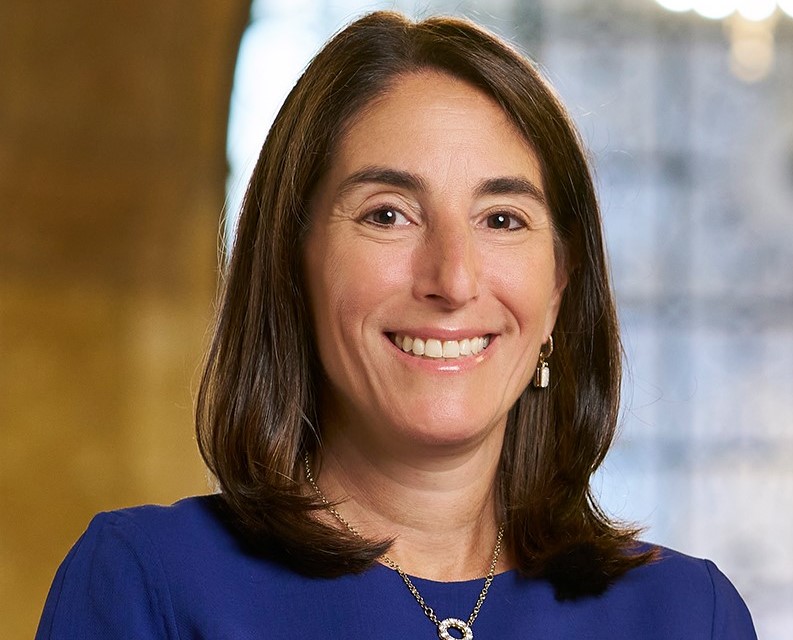
Federal Reserve Bank of Cleveland President Beth Hammack said Friday that the recent surge in U.S. government bond yields appears to be driven primarily by higher real interest rates rather than growing concerns about inflation.
Speaking at the Cleveland Fed’s Inflation: Drivers and Dynamics Conference, Hammack said the increase in real rates has been larger than the shift in market-based inflation expectations. The Cleveland Fed hosted the two-day conference on September 24-25.
Hammack said inflation expectations remain “reasonably well anchored,” suggesting investors are not demanding substantially higher Treasury yields because they anticipate a major acceleration in price pressures.
Instead, she pointed to several factors that may be contributing to rising bond yields, including a resilient U.S. economic outlook and intense competition for investment capital as technology companies pour money into major projects.
Heavy spending across the technology sector, particularly on infrastructure and other capital-intensive investments, can increase demand for financing and compete with government bonds for investor funds. That dynamic may contribute to higher borrowing costs as markets adjust to increased capital demand.
Hammack also said investors are repricing bonds in response to changing expectations for Federal Reserve monetary policy. Shifts in the expected path of interest rates can have a significant effect on Treasury yields, particularly as traders reassess how long borrowing costs may remain elevated.
Her comments put the focus on real yields—the return investors receive after accounting for expected inflation—as a key factor behind the recent bond-market selloff.
The Cleveland Fed closely tracks inflation expectations using a model incorporating Treasury yields, inflation data, inflation swaps and survey-based measures. Its latest estimates provide measures of expected inflation as well as real interest rates and inflation risk premiums.
Hammack’s assessment suggests the rise in Treasury yields may reflect expectations for stronger economic activity, increased demand for capital and adjustments to the Federal Reserve policy outlook rather than a significant deterioration in investors’ confidence that inflation will remain contained.







